

Every quarter, we try to go through as many calls and transcripts as possible. We are not reading them only to form a view on each company. The value of reading widely is in the cross-section: noticing things that may show up in individual companies before they become visible in the aggregate.
But before anything else a word of caution. We are not calling for a bearish phase for Indian equities. We remain fully invested most of the time, and we have learned the hard way that it is usually a mistake to position a portfolio against a large, durable macro trend. What we try to do instead is understand where the soft spots are. That helps us avoid building unintended concentration in areas where a slow-moving trend may be quietly working against a particular sector or a combination of sectors.
This post is about one such slow moving trend. This quarter, we went through various NBFC and consumer-finance earnings calls (Bajaj, SBI Card, Tata, Poonawala and son ). The broad message from the sector was reassuring: retail asset quality remains largely under control.
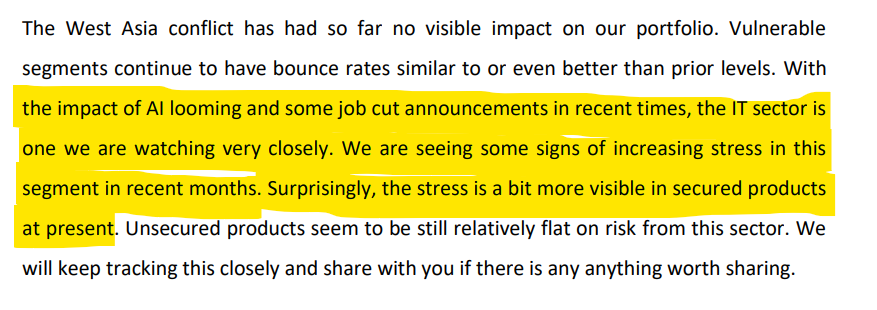
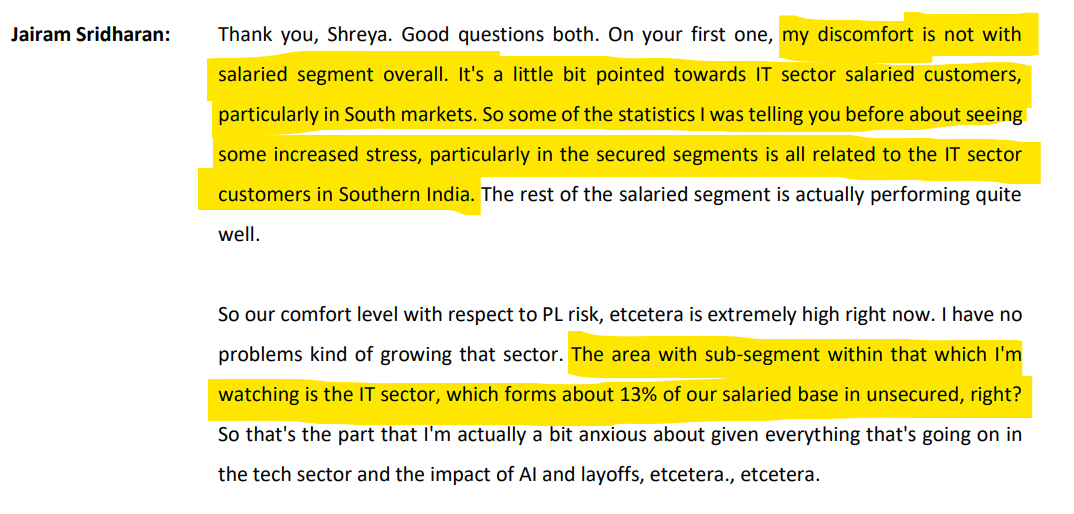
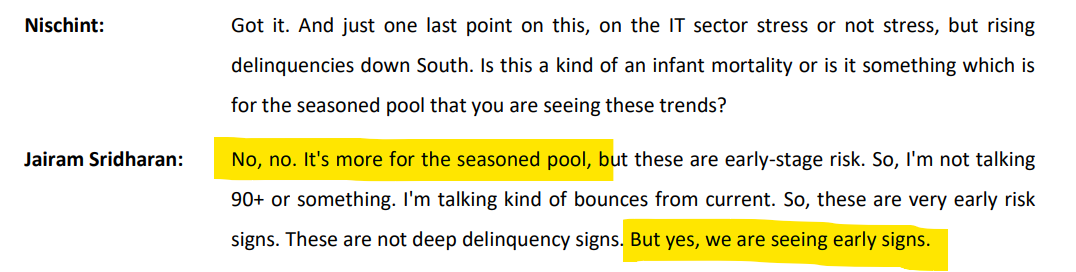
But there were two companies which made a different comment as compared to the rest. In BFSI, one discomforming comment is of much higher value than 100 conforming comments. Both of these comments were pertaining to some emerging stress among the same borrower segment: salaried employees in the IT sector.
This, by itself, does not make a trend. But it is an unusual enough observation to warrant a closer look: Why is this showing up now? Why in secured lending? Is this specific to the portfolios of these two lenders, or is it an early sign of something broader happening to the white-collar borrower? And, perhaps most importantly, what would we need to see over the next few quarters for this to become a signal rather than noise?
The two calls
Here are the two observations that stopped us. We would suggest reading the highlighted lines slowly, because the specific words matter.
First, let’s see some snapshots from the Piramal Finance’s latest call:
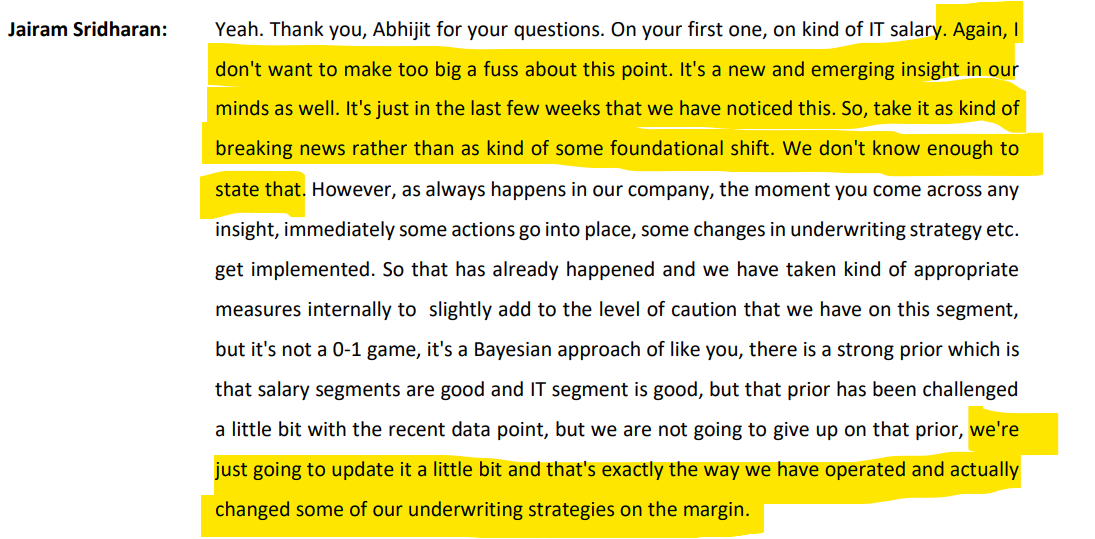
Coming to second:
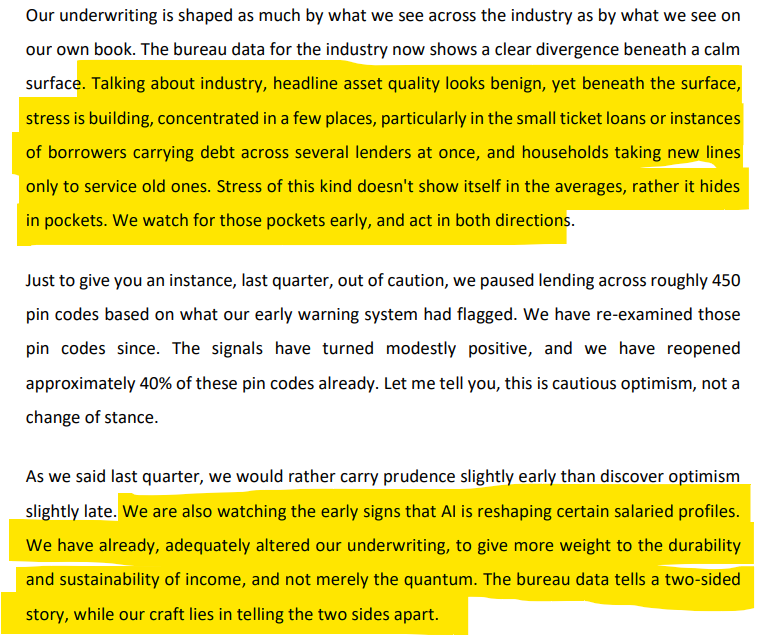
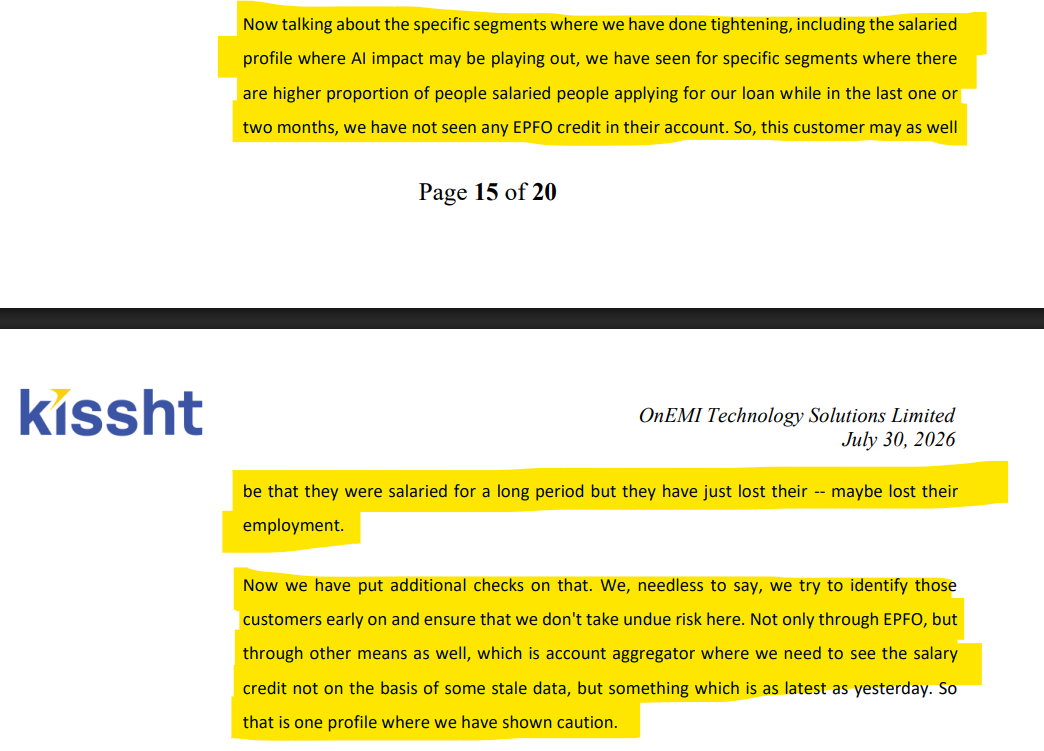
A lender has stopped trusting the fact that somebody has been salaried for years, and has built a live employment check out of provident-fund credits and bank-statement recency. Two lenders, two weeks apart, circling the same thing from different angles, while no one else has cautioned on this. This dichotomy in commentary is why we took it seriously.
What the other seven said
An outlier is only interesting once you have checked it against the others. Let’s see the stance of other BFSI companies on this subject.
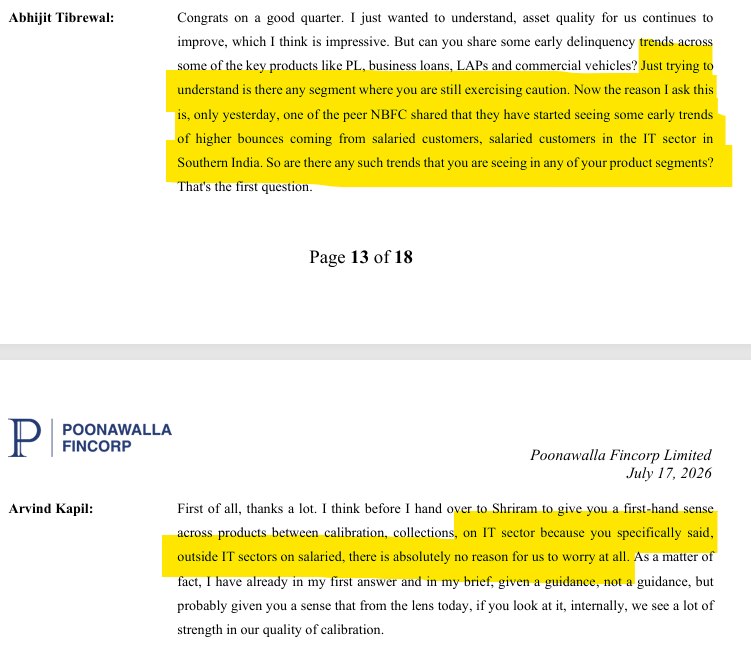
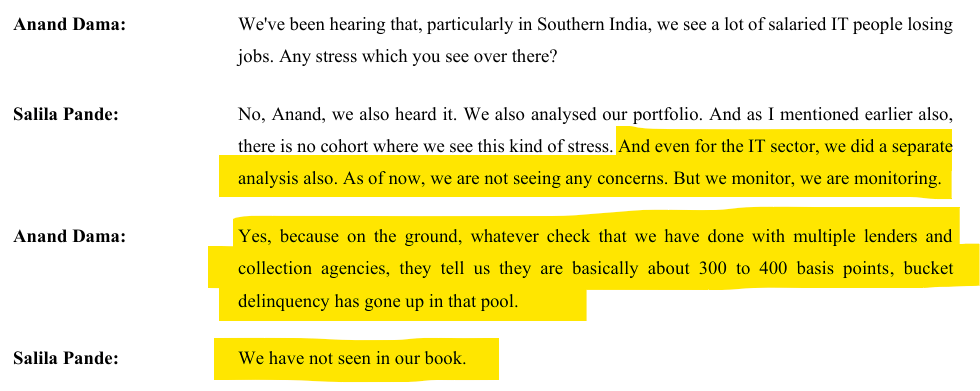
Interestingly, independent ground-level channel checks pointing to a 250–400 basis point rise in early-bucket delinquency in the IT salaried pool (done by Anand Dama of Nuvama as shown in the above snapshot). Only two lenders accepted some stress while majority of BFSI players have not experienced it ‘yet’.
That is exactly what an early, localised signal looks like before it either fades or becomes a bigger problem. When I joined Bowhead back in 2014, my first sector was BFSI where I spent disproportionate amount of time. That time only a handful of banks were hinting to stress in the steel sector which later became one of the biggest write-offs for the entire sector.
It is also why the large books not seeing it is not reassuring in the way it first sounds. A big diversified book is the last place a small, concentrated, early problem shows up, not the first.
Importance of IT Sector employees
The salaried IT employee has, for twenty-odd years, been the premium borrower in Indian retail lending. Documented income, provident-fund credits, an employer with a listed parent, a salary that rose every year. If you were building a retail book from scratch, you started here. When microfinance or a commercial-vehicle book goes through stress, everyone knows that these pools are cyclical. This pool has no recent precedent for going wrong.
Then the second point, which is the genuinely odd one. The stress showed up in secured lending first. That is backwards. A secured loan has collateral behind it, so the borrower fights hardest to protect it; stress conventionally travels from unsecured to secured, not the other way.
And the third point is on broader implications. Consider this:
Karnataka and Telangana together are 16% of India’s direct tax collections (CBDT, FY25), from about 8% of the population.
Bengaluru Urban alone is 40% of Karnataka’s GDP, with district per-capita income nearly four times the national figure.
Bengaluru, Hyderabad, Pune and Chennai are 49% of the top-seven cities’ housing sales.
So the transmission runs job → income growth → housing, consumption, stamp duty and state tax, in a handful of cities that contribute far above their population. You do not need a portfolio full of IT stocks to be exposed to this. If you own South-India-facing housing finance, urban discretionary consumption, premium real estate, or the banks lending into those cities, you are already exposed to it. As a whole, if Gov collects lower taxes, it spends lesser elsewhere which impacts consumer demand overall and hence nothing is safe (simplistically).
What could be driving it
If it is not mass firing, what is it? The answer is in the same season’s IT-company calls, and it is consistent across all nine of them.
We read the June-quarter filings of the top IT services companies as captured the employee hiring trends as shown below:
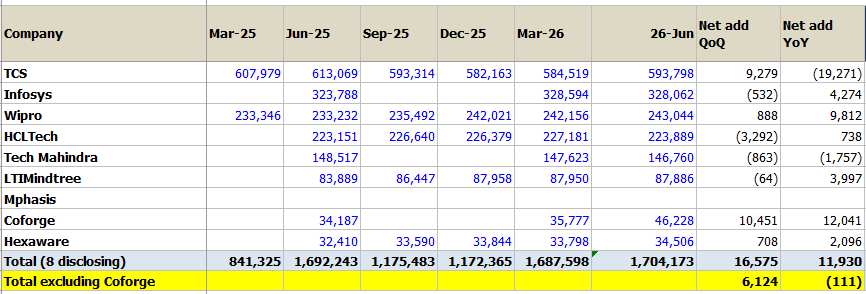
On a twelve-month view, excluding Coforge which made the acquisition, the other seven come to -111. Now one would think there would be some mass layoffs that would have led to this number. Nobody announced a layoff, and that is the point. A few reasons being: Not backfilling: Tech Mahindra’s IT headcount is down 6.6% because AI tooling “has meant lower headcount… we have not had the need to backfill as much as we traditionally would have.” A narrower pyramid base: LTIMindtree’s CFO said the pyramid is going “from the traditional pyramid to a more diamond shaped structure”, and TCS has cut fresher offers to 25,000 from ~44,000.
Another trend that is noticeable is discount demanded by IT sector customers or AI-led price deflation. TCS's CEO put the client give-back at “10% to 15%.” LTIMindtree's mentions that deflation is running at 15%: “the same scope of work I am picking up at… 15% less.”
We are not forecasting a collapse in IT employment. The more useful question is what a modest slowdown in hiring could look like, because modest changes are enough to have a meaningful impact over time. With attrition at roughly 13%, an industry employing six million people sees around 780,000 employees leave voluntarily every year. It therefore needs to hire roughly that many people simply to keep the workforce size unchanged. That makes gross hiring the key variable.
If hiring falls by 1/3rd from the level required to maintain the workforce, the industry could end up with a workforce roughly 10% smaller over five years. If hiring falls by half, the workforce could be around 20% smaller. Neither scenario requires a wave of layoffs. The adjustment happens gradually, through lower replacement hiring and natural attrition. There is already evidence that this process has begun at the margin. TCS has cut fresher intake by 43%.
Stress in the Secured Book
While this does not explain the stress being reported in the secured book, which remains an open question, there is a second-order possibility.
The person who bears the impact of IT sector hiring freeze or net decline is not necessarily the current IT employee, who may continue to keep her job. It is the household that never forms: the graduate who does not get the offer, does not move to Bengaluru, and does not become the marginal buyer of a flat in 2029.
And if the marginal buyer disappears, the adjustment eventually has to happen through price. This is where the two observations: weaker IT hiring and stress in secured lending, potentially connect.
A meaningful part of what this cohort has bought over the last few years has been under construction, often on construction-linked payment plans. These purchases were made against an expectation of continued income growth and, in many cases, continued appreciation in residential property. Appreciation was the equity cushion.
If the incremental demand for housing falls, it will eventually lead to flattish housing prices or worst decline (which doesn’t happen in India though, but you never know). For a borrower who bought a leveraged property on the assumption that it would appreciate, a flat or declining market can be surprisingly uncomfortable.
The apartment may end up being worth roughly what is owed against it or lower, leaving no profitable exit or actually a loss. For someone with a job related anxiety due to AI alongside EMI burden with a possibility of loss on a leverage trade, default becomes a necessity than a choice.
There is a precedent people sometimes forget. After 2008, Karnataka’s stamp-duty receipts fell in absolute terms for two consecutive years, while on the NHB index Bengaluru residential prices did not regain their 2007 level until late 2011.
Ending words
So what would turn this from noise into a signal? The next two or three quarters should tell us. First, whether the early-bucket stress at Piramal actually migrates into later buckets; for now, the company says nothing has moved into 90+ or NPA. Second, whether deferred wage hikes at IT companies actually come through. Coforge may not raise salaries at all this year, Infosys has pushed its cycle to October and January, and Tech Mahindra has staggered its increases. If these are deferred again, the cohort we are discussing could enter a second consecutive year of near-zero real income growth, precisely when a stalled EMI can become a missed one. Third, whether organic IT hiring turns positive once acquisitions are stripped out. If September shows genuine headcount growth, the flat June quarter may simply reflect better utilisation of existing capacity.
As mentioned in the beginning of this post, this is not a bearish call on Indian equities; it is a note to ourselves about one pocket where a slow-moving change may be working quietly against a long-held market assumption: that the salaried IT borrower is among the safest names in the book.
If you would like to understand our research process in more depth or explore how our advisory services can support your investment journey, you can reach us at gaurav.a@nineonecapital.in or fill in the form here (link).
Important Note and Disclaimer: Nine One Capital is a SEBI Registered Investment Adviser (Registration No. INA000018814). This article is not a buy/sell recommendation. We could be wrong, and investors must do their own due diligence before taking any position. Please note that this note is shared only for the education purpose and in no way, it constitutes any buying or selling recommendation. Past performance is not indicative of future returns. Investments in the securities market are subject to market risks. Read all the related documents carefully before investing. Registration with SEBI, BASL membership and NISM certification do not guarantee performance or assure returns.
I would never gone this much deep and connected the things like this article have done
very much thankful to the team who puted a lot in such a small article
Loved this and would love to connect with research team
Gaurav, one troubling disconnect for me in this article is why is there a stress in IT salaried employees TODAY? The net hire number is zero, so that means that employees aren't being laid off. There is inter company churn so the current IT sector employees are finding jobs (in case of retrenchment) in another IT company. If my assumption is correct, then why is there a default and that too in the secured book. Assuming that some IT workers (eg the younger lot) who are cash strapped and still awaiting their annual increments need to default on their EMI, then logically they would do so on a credit card payment or CC loan or a personal loan etc etc. Why jeopardize a vehicle or a house? Perhaps you could clarify