

We generally stay away from investing in newly IPO-ed companies. There is no track record as a public company, no history of what management promised and what they delivered. Most of the time, IPOs are priced to perfections with good storification and dressed up numbers.
But we read the prospectus and first presentation/ con call after listing anyway. Partly this is how we take the market’s temperature: the quality of what gets sold, and at what multiple, tells you more about where we are in the cycle than any index level. Partly it is because, every so often, the primary market brings a genuinely new business model to the exchanges, something with no listed comparable. Those exercises pay for themselves even when we never buy the stock.
Waterways Leisure Tourism Ltd, the company behind Cordelia Cruises, listed on 1 July 2026, is the second kind. There has never been a listed ocean cruise operator in India. We went through the prospectus, ppt and transcripts to understand how Cruise economics work. We also spent sometime in understanding the global cruise companies. However, there was one challenge which could not get over with - the promoter entity which makes this company uninvestible for us.
The interesting part - Cruise Business
Cordelia is India’s only domestic ocean cruise line. One ship, the Cordelia Empress, a 1990-built, 796-cabin vessel, sailing 2- to 10-night itineraries from Mumbai and Chennai to Goa, Kochi, Lakshadweep, Visakhapatnam, Puducherry and Sri Lanka. The company claims roughly 79% of India’s ocean cruise market by value, has carried over seven lakh guests since September 2021, and sells 62% of its cabins directly.
The June 2026 quarter, reported three weeks after listing, had a 105% load factor. That is not a typo: cruise capacity is measured at two berths per cabin, and a figure above 100% means third and fourth berths in family cabins are being sold. In a quarter where the company’s fuel cost per unit of capacity rose 65% because of the Middle East situation, it still reported a ₹23 crore profit and a 4.3% higher average ticket.
The operating record has absorbed real shocks along the way (October 2021 narcotics raid on a sailing chartered to a third-party event company, COVID outbreaks in January 2022, a port denial at Puducherry in 2022). Despite all these hardships, the ship has kept sailing at rising prices.
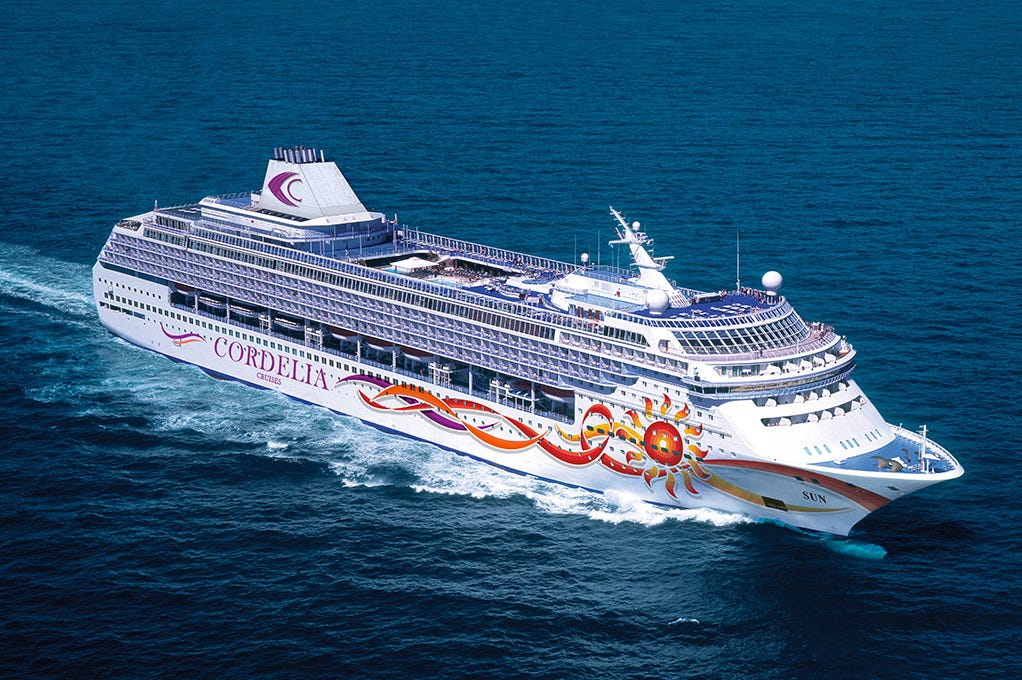
The expansion is what makes it a theme. Two ships arrive on ten-year charters from Norwegian Cruise Line: the Cordelia Sky (ex-Norwegian Sky, 1999-built, 1,002 cabins) starts sailing from Mumbai on 23 October 2026, and the Cordelia Sun (ex-Norwegian Sun, 2001-built, 968 cabins) follows in November 2027. Berth capacity goes from 1,592 to 5,532, 3.5x in fourteen months. The new ships are not just bigger; they are better configured for what Indians actually buy. The Empress has 75 premium cabins (suites and balconies). The Sky has 260. The Sun has 432. As per management, constraint on revenue has never been price, it has been the number of premium cabins available to sell.
One datapoint which makes it more interesting: Cordelia earns 8.7% of its revenue onboard: food upgrades, beverages, spa, shore excursions. Carnival, Royal Caribbean and Norwegian earn 31–36%. Some of that gap is structural (drinking habits, casino regulation), but much of it is hardware: the Empress has three restaurants; the Sky has nine to eleven venues and the Sun fourteen. If even half the gap closes over five years, it is worth eight to ten points of EBITDA margin at unchanged ticket prices.
Add the surrounding tailwinds, the Cruise Bharat Mission targeting a doubling of sea-cruise passengers by 2029, cruise penetration in India at roughly 0.01% of population against ~5% in developed markets, a consumer visibly trading up into experiences, and you have the full checklist: unique consumer-facing franchise, discretionary-spend play, contracted capacity growth, government mission behind the sector, a scarcity premium (there is nothing else to buy for this theme).
This is the recipe from which the market manufactures theme stocks. We would not be surprised if this becomes one. However, one thing makes it uninvestible for us as discussed below.
The promoter behind the company
The promoter of record is a Mauritius company called Global Shipping and Leisure Ltd, holding 89.35% post-issue, itself 100% owned by one individual: Mr. Rajesh Chandumal Hotwani, a 55-year-old resident of Quatre Bornes, Mauritius. His direct holding in the listed company is 100 shares. The prospectus describes his experience as eleven years in entertainment and media and ten in infrastructure, media consultancy and corporate restructuring. No shipping or cruise background is claimed.
The abridged prospectus adds three words to his biography that most IPO notes did not quote: “Associated with Essel Group.”
Then there is the corporate promoter’s own history, disclosed in the fine print of “History and Certain Corporate Matters”. Global Shipping and Leisure Ltd was incorporated in Mauritius in December 2013 under a different name: Essel Corporation Mauritius Ltd. It was renamed on 15 December 2020.
Now this data Dec 2020 is important:
Through 2019–20, the Essel Groupm the Subhash Chandra family, promoters of Zee, was negotiating with lenders over roughly ₹7,000 crore of debt, selling assets, and cutting its Zee stake to a residual minority.
March–October 2020: Essel’s cruise venture, Jalesh Cruises, collapsed. More on this below.
November 2020: a newly incorporated company, Waterways Leisure Tourism Private Ltd, purchased the business operations and intellectual property of Jalesh Cruises. Waterways had been incorporated on 2 November 2020. Trade press at the time described it as a venture of the US-based Dream Hotel Group.
2 December 2020: Royal Caribbean’s Empress of the Seas was sold, becoming the Cordelia Empress. Its registered owner became Stella Seaway Ltd, a Bahamas SPV.
15 December 2020: Essel Corporation Mauritius Ltd became Global Shipping and Leisure Ltd.
The same month the cruise line was created and its ship acquired, the promoter vehicle stopped carrying the Essel name.
Dream Hotel Group, publicly announced as the founder in 2020, appears nowhere in the 2026 prospectus. How that interest was extinguished, and how Mr. Hotwani came to own the Mauritius promoter: when, from whom, for what consideration? All of this information is not disclosed in any document.
The Jalesh lineage
Cordelia is not merely adjacent to Jalesh. It is Jalesh, re-flagged.
Jalesh Cruises was launched by the Essel Group in April 2019 with one ship, the Karnika. It stopped sailing in March 2020 and never resumed. What followed is documented in the maritime press: crew went unpaid for over three months; roughly sixty of them were stranded aboard a ship that was arrested by the Admiralty Court at Mumbai on creditor claims, at anchor without adequate fuel or power; promised reimbursements for evacuation flights were never paid. In November 2020 the Karnika was judicially sold for USD 11.65 million and was broken up at Alang.
That same month, Waterways bought Jalesh’s business and intellectual property. The CEO of Jalesh, Mr. Jurgen Bailom, a career cruise executive from Pullmantur and the Royal Caribbean system, became the CEO of Waterways, and colleagues moved with him. He is today the Chairman, Executive Director and CEO of the listed company. The FY24 accounts contain the receipt for the transaction: an exceptional write-off of ₹14.4 crore, being the full impairment of the “Jalesh” trademark the company had bought.
Another noteworth detail: In 2019 Mr. Chandra founded a domestic industry body, the Indian Cruise Lines Association, with Mr. Bailom as its chairman, headquartered at Marathon Futurex, Lower Parel. The registered office of the listed Waterways Leisure Tourism today is A-1601, Marathon Futurex, Lower Parel.
The collapse itself is nowhere described in the prospectus. The CEO’s biography lists “Zen Cruises Private Ltd”, Jalesh’s operating entity, among his prior engagements without elaboration, and the Jalesh name otherwise surfaces only as the impaired trademark in the financial statements.
The Related Party context
The problem is not that there is a historical association with the Essel Group. The problem is the related party transactions with the Essel ecosystem, without ever calling it a related party.
The loans: In FY24 the company lent ₹5 crore to Essel Green Energy Private Ltd, registered office: Essel House, B-10 Lawrence Road, New Delhi, the group’s Delhi headquarters; last filed balance sheet FY23; two of its three directors also sit on the board of Essel Highways Ltd, which is in insolvency. The loan was repaid within the year. Further, In FY26 it sanctioned ₹20 crore to Maylight Realty Private Ltd, registered at 135 Continental Building, Worli, an address it shares with at least six Essel-named companies; two of its three directors are also directors of Essel MSW Energia Ltd.
The auditor’s remark: The FY2023 legal & audit report says the loans granted that year were, “prima facie, prejudicial to the interest of the Company.” The company’s explanation, printed in the prospectus: “There was a typo error in the audit report.” We have read many prospectuses. We have not before seen an audit finding answered with the claim that the auditor mistyped it.
The structure: The listed company owns no ship directly. The Empress sits inside Bay Cruise Investments Inc., a BVI company that began life in 2009 as Russoli Holding Ltd, was renamed twice, remained under the corporate promoter’s ownership for years, and was sold to the listed company in February 2025, just four months before the draft prospectus. The Empress itself was acquired in December 2023 from Stella Seaway Ltd., a Bahamas SPV administered by Campbell Cruise & Yacht Management, the same firm that manages the company’s technical operations. The purchase price has never been disclosed. The newer ships follow an equally layered structure. Ownership rests with Bermuda-incorporated vessel-owning entities. The vessels are transferred to the BVI subsidiary, novated to a GIFT City leasing entity, and then time-chartered back to the listed company. To fund this arrangement, the company routed 86% of its net IPO proceeds, ₹480 crore out of ₹557 crorr, to the step-down subsidiary as deposits and advance lease rentals. Mauritius, the British Virgin Islands, the Bahamas, Bermuda: every critical ownership layer sits in jurisdictions where beneficial ownership is not publicly disclosed.
Ending Words
Cruise lines are unusually dependent on management integrity. Unlike banks or consumer companies, much of the cost base, fuel, catering, crew, entertainment, port charges, drydocks and charter hire, flows through thousands of vendor contracts that outsiders cannot independently verify. Any leakage would simply appear as a slightly weaker margin rather than an obvious red flag.
At Cordelia, many of the largest cash flows pass through offshore entities beyond public scrutiny. Charter payments will exceed ₹300 crore annually once both new ships are operational. Around ₹100 crore of annual operating costs are outsourced to offshore hospitality and procurement providers, while the technical manager’s fee is not separately disclosed. Empress was acquired from a Bahamas SPV at an undisclosed purchase price. The group has also extended loans to Essel-linked entities and even lent USD 1 million to its corporate promoter through a subsidiary, demonstrating that cash can move across the group structure. None of this proves wrongdoing. But it does mean that shareholders must place considerable trust in management’s judgment and the numbers being reported.
We also want to be precise about what we are are not saying. We have found no evidence that any money has been diverted from Waterways, and SEBI has cleared the offer document. It is entirely possible that Mr. Hotwani is exactly what the prospectus describes: the sole, independent beneficial owner of the promoter entity.
However, every independently verifiable marker: 1) the promoter entity’s historical name, 2) its 2013 objects clause, 3) Mr. Hotwani’s own stated association, 4) the acquired business, 5) the retained CEO, 6) the office building, and 7) the Essel-linked entities that have borrowed from the company, points in the same direction: a continuing connection with the Essel ecosystem that the prospectus never directly addresses.
For us, that is enough. We find the industry attractive, the opportunity unique, and the long-term demand story compelling. But investing is ultimately an exercise in elimination. In businesses where so much depends on management integrity and so little can be independently verified, this remains uninvestable for us.
As the late Rakesh Jhunjhunwala often said, "I reserve the right to be wrong." If future disclosures and governance standards materially improve, we will be happy to revisit our conclusion.
If you would like to understand our research process in more depth or explore how our advisory services can support your investment journey, you can reach us at gaurav.a@nineonecapital.in or fill in the form here (link).
Important Note and Disclaimer: Nine One Capital is a SEBI Registered Investment Adviser (Registration No. INA000018814). This article is not a buy/sell recommendation. We could be wrong, and investors must do their own due diligence before taking any position. Please note that this note is shared only for the education purpose and in no way, it constitutes any buying or selling recommendation. Past performance is not indicative of future returns. Investments in the securities market are subject to market risks. Read all the related documents carefully before investing. Registration with SEBI, BASL membership and NISM certification do not guarantee performance or assure returns.
As always very well articulated and details of your forensic analysis is excellent. I liked “ But investing is ultimately an exercise in elimination”
OMG!!!
So many red flags. And the ultimate link to a drowning Essel/Zee group is a very serious red flag. The layered ownership and operational structure raise serious doubts. Market will ultimately find out all these things over a period of time and one who holds the pillow last when the music stops will face the wrath.