

What better day to write about RBZ Jewellers than today. Yesterday the company inaugurated its second showroom, in Surat, and kickstarted its retail expansion journey with Vicky Kaushal. One thing before we begin. This is not an investment recommendation. We hold the stock, our clients hold the stock, and you should read every word here as coming from biased investors. What follows is simply how we think about the business, written the way we would explain it to a friend across the table.
RBZ (NSE: RBZJEWEL) is an Ahmedabad company doing two things: it manufactures antique and bridal gold jewellery for most of the big national chains, and it runs retail showrooms under the Harit Zaveri Jewellers name. Until yesterday there was one showroom. That one showroom did ₹408 crore of revenue in FY26. By the time the wedding season peaks, there will be five. Whether the new stores ramp the way the first one did will decide whether the market keeps seeing RBZ as a B2B workshop with a shop attached, or starts seeing a retail franchise in the making. We believe in the second one and explain in this note our reasoning for the same.
Difference among the Jewellers
Everyone thinks that jewellery should be in the discretionary bucket of consumption, and occasion wear is the most expensive jewellery there is. However, one should imagine how an Indian family actually behaves. The mother-in-law does not arrive at the engagement with a light gift. The bride does not wear something ordinary on her wedding day. What she wears announces where the family stands, in front of the one gathering whose opinion the family cares about most. When gold ran up last year, weddings did not stop; purchases got postponed by a few months and then happened anyway. Harit Zaveri said it in plain words on the August earnings call: daily wear is bought in moments of joy, but “occasion wears are purchased on the compulsory basis.”
So this is a discretionary product on paper and a compulsory one in practice. In our years of looking at consumer businesses we have found very few categories with that combination, and it is worth paying attention when one of them is available at a sensible price.
The second thing to get right is what not to compare it with. A large part of Indian jewellery retail, especially the South-centred model, sells gold that happens to be wearable. The customer is buying the metal, making charges run from 3% to maybe 10%, and shops compete on price per gram. It is a fine trade, but it is a different trade. RBZ’s world is antique, polki and jadau bridal work, design-led and karigar-intensive, where making charges run 20% to 40% of the gold value. The customer is paying for craft, and for how the piece will look in the photographs she will keep for fifty years and eventually will pass it on to the next generation.
Institutional & Retail Segments
Unlike many other listed jewellery companies, RBZ has an institutional (B2B) as well as retail business. From its manufacturing facility in Ahmedabad, RBZ supplies antique and bridal jewellery to 190-plus retailers. The company’s own presentation names Titan, Malabar and Senco among the clients. The chains are consolidating their vendor base, moving from scattered karigar networks to organised suppliers who can deliver volume, quality and design secrecy with clean GST and hallmarking. There are very few organised manufacturers of this particular category. Our channel checks with people at the large chains have been uniformly good on RBZ’s workmanship and delivery.
Key thing to note here is that a big share of B2B volume is job work: the client sends its own gold, RBZ does the conversion and bills only the making charge. This results in small revenue booking but really high profit margin. In the September 2025 quarter, about 250 kg out of 380 kg of B2B volume was job work. So the reported top line understates the true size of the business, and the quarterly mix between job work and outright sale swings the revenue and profitability margins by a wide margin.
Coming to the B2C part, there is a single showroom in Ahmedabad. It did ₹24 crore in FY21 in its first full year, and ₹408 crore in FY26. On the August 2024 call, management said the store could some day reach ₹400 to ₹500 crore; it crossed ₹400 crore within two years of saying so. On roughly 100 kg of inventory, about ₹150 crore of gold at today’s price, the store turns its stock about 2.7 times a year.
Unit Economics
Now that RBZ is going to expand its retail showrooms aggressively, it makes sense to spend sometime on understanding what it takes to launch a showroom (capital investment) and what kind of profits does one showroom generate.
The math is fairly simple. One kilo of gold inventory costs about ₹1.5 crore today. Turn it twice a year at a 15% gross margin and it gives you ₹3 crore of revenue and ₹45 lakh of gross profit, below that are staff, rent and marketing, all small with marketing being bigger in the beginning and keeps reducing as the showrooms age.
A 10,000 sq ft showroom costs about ₹7 crore to fit out. The gold inside it costs about ₹187 crore. The interiors are under 4% of the money employed. Done this way, jewellery retail expansion is closer to buying bullion with a shop attached than to building stores. The capital is recoverable, bankable and, as we will see, hedgeable.
Here is our working model of one large-format store, the Surat and Rajkot size, at current gold prices:
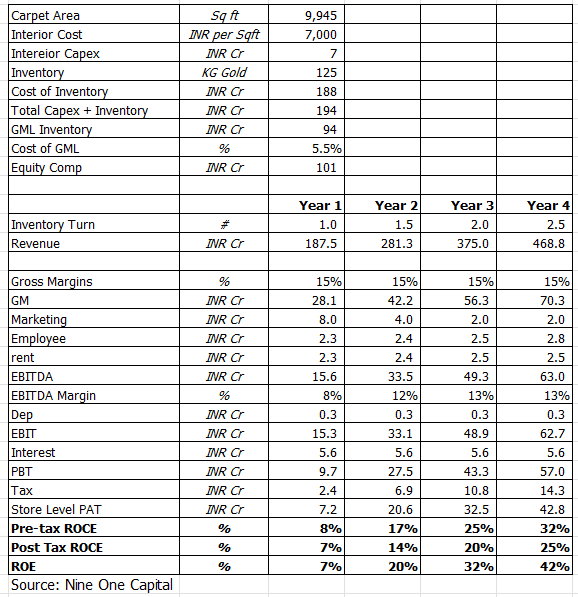
What is interesting is that in year 2 itself, the showrooms make 20% post tax ROE. Reason why RBZ makes higher GMs is because of its in house manufacturing which also leads to RBZ selling designer jewellery at 10-20% lower making charges than the large retailers.
One showroom becomes five
The rollout is timed in a highly optimal manner. Surat opened yesterday, well before Navratri, with Vicky Kaushal doing the honours and the whole wedding and festival season ahead of it. Rajkot, the other flagship-sized store, is slated to open next in October. Two mid-format stores, Maninagar in east Ahmedabad and Gandhinagar, follow in November, in time for the wedding season.
All four showrooms opening in a tight three month period is an indication of what RBZ is going to be. Three more Gujarat stores are planned for FY28. Seven new showrooms over two financial years, against one since listing. RBZ is also aggressive in its marketing push and has allocated ~₹25 crore of marketing for the year.
We have heard the same pushback from multiple investors: the market will not assign much value to a company with just one showroom and will wait for management to execute its growth plans. Our view is that this is precisely where the opportunity lies.
If the company successfully executes the next four showrooms, demonstrates that new stores can break even in Year 1 and turn significantly faster in Year 2, what is currently just a one showroom story becomes a repeatable business model visible to the market. Companies get re-rated when that transition happens.
The flywheel
Now put the pieces together, because this is the part we like most: the growth pays for itself.
A mature showroom throws off cash. The flagship’s gross profit alone runs around ₹60 crore a year at current turns. That cash becomes the gold inventory of the next store. The next store ramps from one turn towards two and a half, starts generating its own surplus, and the wheel goes around again.
Gold metal loans make the wheel spin cheaper and safer at the same time. We wrote about this in our last post here. Watching RBZ adopt the tool in the very year its inventory footprint multiplies across five locations is something which is well timed and an indication of what lies ahead.
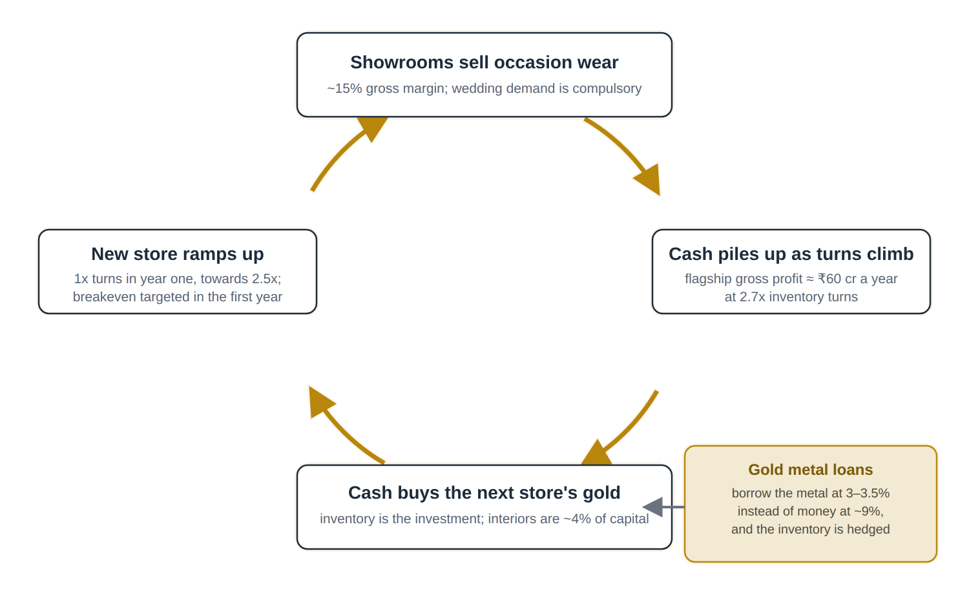
And most importantly, due to the above flywheel, there is no plan to raise equity. Growth that comes without dilution belongs entirely to the people already holding the shares. Most of the companies that we have at Nine One Capital recommendation list exhibit this trait.
Final words
We have known Harit Zaveri since the IPO, and a few plain observations about him carry more weight with us than another tab in the model. This is his only business. He built the showroom himself, taking it from zero to roughly ₹400 crore in six years. The retail brand carries his own name, which in the jewellery business of Gujarat is more than a branding exercise; it is a personal guarantee.
He continues to attend institutional exhibitions himself and remains involved in building the B2B business. Guidances over the quarters have always been out performed. We asked him his vision for RBZ and he says he wants RBZ to become the most respected jewellery company in the country. He may or may not get there. But after meeting promoters across the sectors, we have learnt to pay attention to what a promoter is optimising for. In a trust-driven business like jewellery, we would rather see a promoter building for reputation over decades than one optimising solely for the next quarter. As always, we could be wrong; that is exactly why the checkpoints above matter more than our opinion.
At Nine One Capital, we spend a significant amount of time building the right analytical foundation before forming a view on any company. If you would like to understand our research process in more depth or explore how our advisory services can support your investment journey, you can reach us at gaurav.a@nineonecapital.in or fill in the form here (link).
Important Note and Disclaimer: Nine One Capital is a SEBI Registered Investment Adviser (Registration No. INA000018814). This post is for education and information only. It is not investment advice, a recommendation, or a solicitation to buy or sell any security. Nine One Capital is a SEBI-registered Investment Adviser (Registration No. INA000018814). We and our clients hold positions in RBZ Jewellers, and our view is accordingly not neutral. Figures are from company filings, investor presentations and earnings-call transcripts, and from our own estimates where stated; they may contain errors. Investments in the securities market are subject to market risks; read all related documents carefully and consult your own SEBI-registered adviser before acting. Registration granted by SEBI and certification from NISM in no way guarantee the performance of the intermediary or provide any assurance of returns to investors.
RBZ is probably where Dmart was in 2006. Dmart too started slow, got the unit economics right and then went on major expansion.
How will it (the expansion plan) play out down the line no one knows but as of now probabilistically it looks quite great.
Thanks Gaurav and team for putting the business model in simplest words.
(Biased and invested)
lots of issues here
primary one being unhedged gold inventory for expansion ( should be ~1.2 lakhs / 10gm)
should gold correct [ low probability but not zero] inventory markdowns by the time newer stores were supposedly do 1.5x turns will stretch
no issues on Receivlables, good quality timing issue in fy26 end, but bank ST WC loan vs gml will realise only when gold holds it value
net net its a gold play; howmuch of it is priced in 13x P/E needs to be calculated in context of margin less growth in coming 4-6 Qs of ramp